Difference Between Bookkeeping and Accounting

Difference between bookkeeping and accounting

The difference between bookkeeping and accounting can be confusing if you’ve never worked with an accountant. Bookkeeping is the day-to-day job of recording and organising your business’s financial transactions. Accounting takes that information and uses it to show how the business is doing, prepare your accounts and meet your tax and reporting obligations. In short, bookkeeping creates the records and accounting makes sense of them.

If you’ve never worked with an accountant, the two terms are easy to mix up. Plenty of business owners do, so here’s what each one actually involves.

What is Bookkeeping?

Bookkeeping means keeping a clear, up-to-date record of the money coming into and going out of your business. Everything else is built on it.

In practice, that means recording your sales and purchases, logging business expenses and keeping invoices and receipts in order. It also means reconciling your bank transactions, which just means checking that your records match what has actually gone through the account. You can do this yourself or hand it to a bookkeeper, but it needs doing regularly, whether that’s weekly or monthly.

Done well, bookkeeping gives you an accurate picture of what’s happening day to day. You can see who owes you money, what you’ve spent and what’s come in, without digging through a pile of paperwork.

What is Accounting?

Accounting picks up where bookkeeping leaves off. An accountant looks at your financial information, reviews it and uses it to tell you something useful about the business.

That includes preparing your annual accounts and supporting your tax and compliance requirements. But it goes beyond that. A good accountant can show you how profitable you really are, help you make decisions with confidence and plan for what’s coming next.

So accounting isn’t only about filing a tax return once a year. It’s about understanding the numbers and what they mean for you.

What is the Difference Between Bookkeeping and Accounting?

The simplest way to remember it:

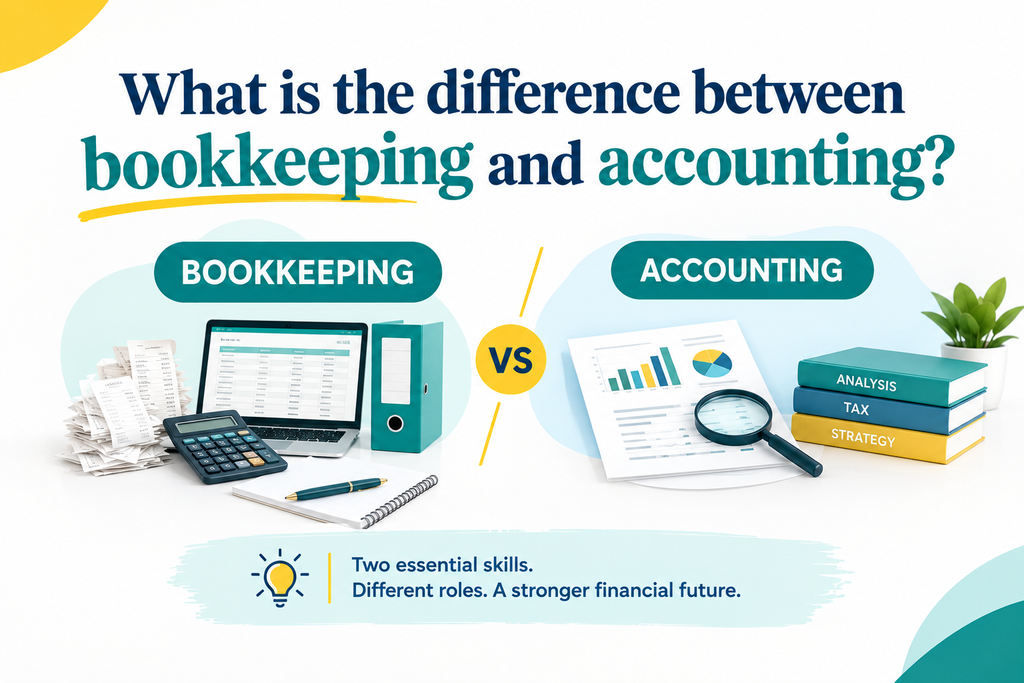
Bookkeeping = recording and organising financial information

Accounting = reviewing, interpreting and using that information

BookkeepingAccounting
Main purposeKeep accurate, organised recordsUnderstand the numbers and meet reporting and tax requirements
Typical tasksRecording transactions, reconciling bank accountsPreparing accounts, supporting tax work, giving advice
TimingOngoing, day to dayPeriodic, such as year end, plus advice when you need it
Who may provide itYou, a bookkeeper or an accountantAn accountant
How it helpsA clear view of day-to-day activityInsight, planning and compliance

Does My Small Business Need Both?

Many businesses benefit from both, but how much support you need depends on how big and how complicated your business is. You don’t have to pay for both.

A very small business might handle its own basic bookkeeping and bring in an accountant for the year-end accounts and tax. As the business grows, it often makes sense to pass the bookkeeping to someone else so the records stay accurate, leaving the accountant free to focus on accounts, tax and advice. A more established business may want regular bookkeeping alongside ongoing accounting support and regular financial reports.

Here’s how it can look in real life. A self-employed joiner records every invoice they send and every cost they pay, such as materials, fuel and tools, and matches it all against the bank. At year end, their accountant takes those records and prepares the accounts, works out how profitable the business has been and completes the tax return. They might also point out that material costs are creeping up, which gives the joiner something to act on.

What Happens if My Bookkeeping is Not Up to Date?

Nothing dramatic happens overnight, but problems tend to pile up quietly.

You may not know where the business really stands. Transactions can go missing or get recorded wrongly, which makes the accounts harder to prepare and leaves you with a mountain of work at year end. Business decisions become guesswork, and you may find gaps in the records you need for tax.

Catching up on months of receipts and bank entries takes far longer than keeping on top of them as you go.

Which one does my business need?

Have a think about these questions:

  • Do you keep your financial records up to date?
  • Do you know how profitable the business is?
  • Are you confident your records are accurate?
  • Are you comfortable preparing the information needed for your accounts and tax return?
  • Do you need regular financial advice or planning?

If keeping on top of the records is the sticking point, bookkeeping support may be what you need. If you’d like help understanding the numbers, planning ahead or sorting out your tax, you’re probably looking for an accountant. Plenty of businesses end up needing both.

At Magnum Accountancy, we help small business owners work out what level of support suits them, whether that’s a little help at year end or something more regular.

Book a free call with Daxa at Magnum Accountancy.
Choose the Right Accountant for Your Small Business

choose the right accountant for your small business

Choosing the right accountant for your small business can make managing your finances much easier. The right accountant gets your business, does the work you actually need, explains things in plain English and gives you a fee you can understand. Qualifications and experience matter, but so does whether you’d feel happy ringing them with a question. Here’s how to compare your options.

How Do I Choose the Right Accountant For My Small Business?

Start with experience. A sole trader working from a van has very different needs from a limited company with a team, so ask whether they already work with businesses like yours.

It also helps if they understand your industry. They’ll know how you get paid, what you typically spend money on and where the pressure points are, so you won’t be explaining the basics every time.

Make sure they know the rules that apply to you too. Depending on your business, that could mean Self Assessment, Corporation Tax, VAT, payroll or Making Tax Digital.

Then there’s the matter of qualifications. The title “accountant” isn’t protected by UK law, so it’s worth asking any accountant you’re considering whether they belong to a recognised professional body, and which one. You can check their membership by contacting the organisation directly.

Finally, look for someone who gives you proactive advice. Preparing your accounts is the basic job. A good accountant will also flag tax planning, cash flow issues and upcoming changes before you’ve had to ask. For more guidance on hiring an accountant, see ICAEW’s small business guide to hiring an accountant.

What Questions Should I Ask Before Choosing an Accountant?

It helps to go into that first conversation with a few questions ready:

  • What’s included in your fees, and what costs extra?
  • Do you work with businesses like mine?
  • Will I have one person I deal with regularly?
  • How often will we speak, and how quickly do you reply?
  • Do you offer tax planning or business advice?
  • Which accounting software do you work with?
  • Are your fees fixed or hourly?
  • Are you a member of a professional body, and which one?

Pay attention to how they answer, not just what they say. Clear, relaxed answers are a good sign.

Fixed Fee vs Hourly Accounting – Which is Better?

With a fixed fee, you agree a price for a set list of work, usually monthly or yearly. You know what’s coming, so budgeting is easier.

With hourly charging, you pay for the time spent. That can suit one-off jobs or work that’s hard to predict, but your final bill can be harder to pin down.

Plenty of small business owners prefer fixed fees because there are fewer nasty surprises, and you may feel happier picking up the phone without wondering if the meter is running. But neither option is automatically better. Costs vary depending on your business and what you need, so compare like with like and ask exactly what’s covered.

What are the Red Flags When Choosing an Accountant?

Be cautious if you notice any of these:

  • Fees that are unclear or keep changing. If you can’t work out what you’ll pay, ask again.
  • Slow or patchy replies. If they’re hard to get hold of before you’ve signed up, it rarely improves afterwards.
  • No interest in your business. If they don’t ask what you do or how you work, they may not be the right fit.
  • Promises that sound too good to be true. Nobody can guarantee tax savings without seeing your figures.
  • Only available at year end. You want someone you can reach when a decision can’t wait.
  • Vague answers about qualifications. Anyone you hire should be happy to explain which professional body, if any, they belong to.

One of these on its own doesn’t mean you should walk away, but a few together are worth taking seriously.

How Can I Choose the Right Accountant for My Small Business?

Here’s a simple checklist to use when you’re comparing:

  1. Write down what you need, whether that’s bookkeeping, VAT, payroll, accounts, tax returns or ongoing advice.
  2. Ask other business owners in your trade or sector who they’d recommend.
  3. Ask which professional body they belong to, and check with that organisation.
  4. Get a clear written quote showing what’s included.
  5. Find out who your day-to-day contact would be.
  6. Check they’re happy working with your accounting software, or can suggest something suitable.
  7. Ask how often they’ll be in touch and whether they offer proactive advice.
  8. Ask for references from similar businesses if you’d like extra reassurance.
  9. Notice how the first call feels. Did you understand them, and did they listen?

Speaking to two or three firms usually makes the best fit obvious. At Magnum Accountancy, we’re always happy to talk through what you need before you commit to anything.

Book a free call with Daxa at Magnum Accountancy.
Allowable Expenses for Sole Trader Builders

Allowable expenses for sole trader builders

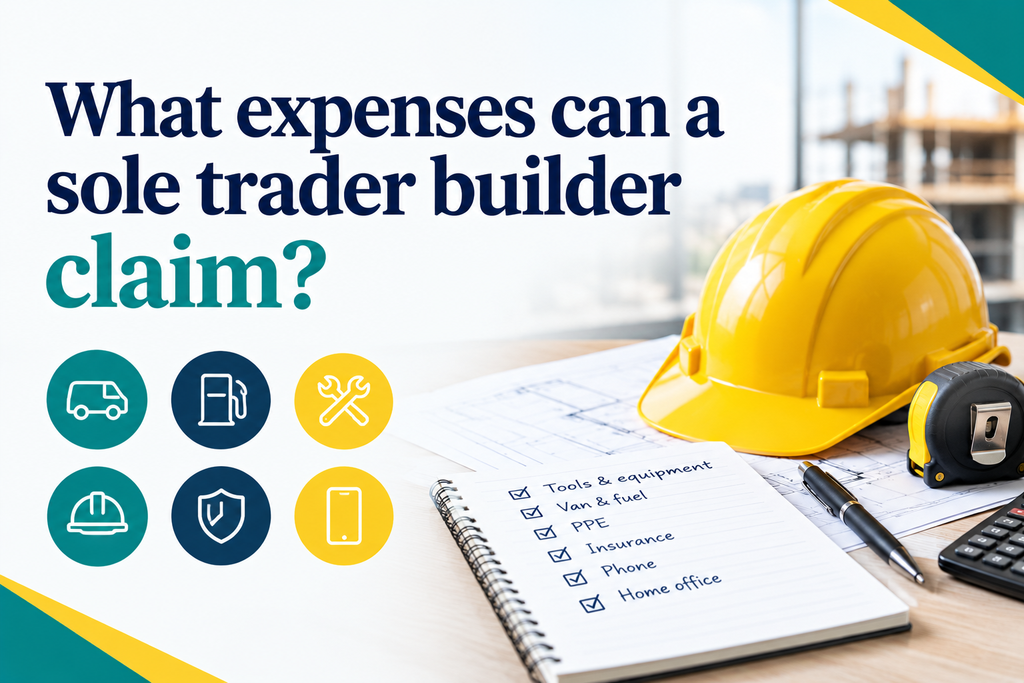
Allowable expenses for sole trader builders can include tools, PPE, insurance and certain van, fuel, phone and home office costs. But not everything you pay for is automatically allowable. The cost has to be genuinely for the business and fit HMRC’s rules, and the answer often depends on how you actually use the item.

What Counts as a Business Expense For a Sole Trader Builder?

Allowable expenses are the everyday costs of running your business that you can deduct before your tax is worked out. They don’t put money back in your pocket. They just reduce the profit you pay tax on.

The test HMRC applies is that the cost must be incurred “wholly and exclusively” for your business. If you use something for both work and home life, you can normally only claim the business share. Bigger purchases, like a van or heavy equipment, may be dealt with through capital allowances rather than as a standard expense. For more detailed guidance on what sole traders can claim, see GOV.UK’s guidance on expenses if you’re self-employed.

Tools, PPE and Equipment

This is usually the easiest category for a self-employed builder.

  • Tools: Hand tools and power tools you use for your trade are typically allowable, and so is repairing or replacing them. Bigger kit may fall under capital allowances instead.
  • PPE: Hard hats, hi-vis, safety boots, gloves, goggles and dust masks are generally fine. Ordinary clothing isn’t, even if you only wear it on site.
  • Other equipment: Things like scaffold hire, skip hire and the materials you buy for jobs are normal construction business expenses.

Say you buy a nail gun and a set of chisels for your next few jobs. They’re bought for the trade, so they’re likely to be allowable, although the exact treatment depends on the item and how it’s used.

Keep the receipt every time, even for small buys. It’s much easier than trying to remember what you spent months later.

Van, Fuel and Travel Costs

If you use a van for work, you can usually claim for it. Vehicle costs come with their own rules, though, so you can’t just claim the lot.

There are two main routes. You can use HMRC’s simplified expenses, which is a flat rate for each business mile, or you can claim your actual running costs (fuel, insurance, repairs and servicing) plus capital allowances on the purchase. You generally can’t mix the two for the same vehicle, so it’s worth thinking it through before you choose.

The big question is business versus private use. Fuel to get to a customer’s site is a business cost. Fuel for a family weekend away isn’t. If the van does both, only the business proportion can be claimed.

Travel between home and a regular place of work is usually treated as commuting, which isn’t allowable. Travel to temporary sites can be different, but it depends on your circumstances.

For example, a builder might use their van for site work all week and for personal trips at weekends. They’d need to work out the business share of the costs, and a simple mileage log makes that far easier.

Insurance, Phone and Home Office Costs

  • Insurance: Public liability, tool cover and employers’ liability (if you take on staff) are typical business insurances. Van insurance is claimable for the business share. Personal cover, such as life or health insurance, isn’t a business expense.
  • Phone: You can generally claim the business proportion of your mobile bill. A separate phone or SIM for work keeps things simple.
  • Home office: If you genuinely use part of your home for business admin, like quotes, invoicing and paperwork, you may be able to claim towards your household costs. HMRC allows either a flat rate based on the hours you work at home or a calculation of the actual business proportion.

A builder who uses one phone to call customers and suppliers, but also to ring family, would normally only claim the business part. The same thinking applies to a spare room used for admin.

Whenever something is part business and part private, the treatment depends on the circumstances, so it’s worth checking before you claim.

What Records Should a Builder Keep?

Good records back up every claim if HMRC ever asks questions, and they make your Self Assessment quicker and less stressful. As a rule, self-employed people should keep business records for at least five years after the 31 January submission deadline for that tax year.

A simple checklist:

  • Receipts for tools, PPE and materials
  • Sales invoices and supplier invoices
  • Fuel receipts and a mileage log
  • Insurance documents
  • Phone bills, with business use noted
  • Vehicle records, including purchase, servicing and repairs
  • Notes on how you split business and private use

If you’re not sure what you can claim, Magnum Accountancy works with self-employed builders and tradespeople all the time and can help you claim what’s right without taking risks.

Book a free 30-minute call with Daxa at Magnum Accountancy. BOOK A FREE CALL
Holiday Pay Enforcement: What Agencies Need to Know

Holiday pay enforcement changes for UK recruitment and staffing agencies

Holiday pay enforcement is quietly turning into a bigger compliance issue for UK recruitment and staffing agencies. The Government is currently consulting on how holiday-pay rights could be enforced in future. If your agency places large numbers of temporary or agency workers, it’s worth understanding this before the consultation closes on 22 September 2026.

What is the Holiday Pay Enforcement Consultation?

At the moment, if the holiday pay owed to a worker is not paid, the main option available is an Employment Tribunal claim. There’s no dedicated body actively going out and checking whether employers are getting it right — it’s largely reactive.

The Government’s “Make Work Pay: Holiday Pay Compliance and Enforcement” consultation, published on GOV.UK, is looking at changing that. It sets out a proposed role for the Fair Work Agency (FWA) — a new body being set up to take on enforcement of certain employment rights — with holiday pay compliance to be actively checked and enforced.

Why does this matter? The FWA would actively oversee holiday pay for the first time, rather than leaving workers to make individual claims. This matters even more for recruitment and staffing businesses with large, changing workforces.

Worth saying clearly up front: everything here is a proposal at this stage. None of it is confirmed law, and the final approach could well look different once the consultation has run its course.

Why Should Recruitment and Staffing Agencies Pay Attention?

Agencies and staffing businesses tend to sit in a slightly different position to a typical employer, and a few things make holiday pay particularly relevant to you:

  • Workforces are often large and constantly shifting, with workers moving between assignments
  • A lot of workers are on irregular hours, which changes how their holiday pay gets calculated
  • Payroll has to apply holiday pay consistently across many workers at once, not just a small team
  • Records need to cover holiday entitlement, holiday actually taken, and how the pay was worked out for each person

Not every agency has the same set-up or obligations. It depends on how your business operates and the workers you place. If you calculate holiday pay inconsistently, stronger enforcement could highlight these issues.

What Could Change for Holiday Pay Enforcement from 2027?

The consultation proposes that FWA enforcement of holiday pay could start from 2027 — though that’s a proposed timeline, not a locked-in date.

Under the proposed approach, the FWA’s role would be part support, part enforcement. The FWA would support employers by raising awareness and providing guidance on holiday pay requirements. If compliance issues arise, the proposals would allow the FWA to investigate claims, carry out workplace checks and take enforcement action where necessary.

One feature worth noting is the proposed “whole employer” approach. The FWA could review holiday pay across an entire business, rather than handling individual complaints. The consultation also proposes a possible civil penalty framework, broadly similar in shape to existing minimum wage enforcement. However, the consultation is still considering the actual details of any penalties, so nothing has been settled yet.

Again — all proposed. The final enforcement approach, the timing, and any penalty structure will depend on what comes out of the consultation.

What Should Agencies Review Now?

You don’t need to wait for the consultation to wrap up before taking a practical look at your own processes. Worth reviewing:

  • How holiday pay is currently calculated across your different types of workers
  • Whether payroll applies holiday pay the same way across the board, rather than varying by team or system
  • Whether worker records are accurate and up to date
  • Whether holiday entitlement and holiday pay records are being properly kept
  • Whether any past payroll or holiday-pay issues are worth a second look
  • Whether you’re keeping up with the latest guidance on holiday pay

This is exactly the kind of thing the team at Magnum Accountancy helps agencies with — going through payroll processes and holiday pay calculations to make sure they’ll hold up, whichever way the enforcement landscape ends up moving.

What is the Consultation Deadline?

The consultation closes at 11:59pm on 22 September 2026. If your recruitment or staffing business has views on the proposed enforcement approach, you can read through the consultation and submit a response via GOV.UK before then.

If you run a UK recruitment or staffing agency and want to review your payroll and holiday-pay processes, speak to Magnum Accountancy.

Book a free 30-minute call with Daxa at Magnum Accountancy. /book-a-free-call/
Construction Accountant: Do I Need a Specialist for My Business?

construction accountant reviewing business finances

Not necessarily. There’s no rule saying a construction business has to use a specialist construction accountant. But once you factor in things like CIS and the VAT domestic reverse charge, an accountant who genuinely knows the sector can save you a fair bit of hassle. Whether that’s essential for you really comes down to your own business.

Why is Construction Accounting Different?

Most industries just handle the basics — bookkeeping, annual accounts, a standard VAT return. Construction has all of that too, but with a stack of extra rules on top: how payments to subcontractors get taxed, how VAT is (or isn’t) charged on certain services, and checks that need doing before you can even pay someone for the first time.

None of it is especially exotic, but it is specific. A general accountant can handle the day-to-day basics just fine; they just might not run into CIS or reverse charge VAT often enough to catch every detail that construction businesses deal with regularly.

What Should a Construction Accountant Understand?

A handful of areas keep coming up for construction businesses, and it’s worth an accountant actually knowing them, rather than figuring them out on the fly.

CIS (Construction Industry Scheme). CIS (Construction Industry Scheme). This sets the rules for how contractors and subcontractors handle tax — broadly, contractors deduct money from subcontractor payments and send it to HMRC. Getting the deduction rate right, and knowing what should and shouldn’t have CIS applied (materials versus labour, for instance), takes a bit of familiarity with how the scheme works in practice.

Domestic Reverse Charge VAT. This applies to a lot of construction services between VAT-registered, CIS-registered businesses, and it flips the usual VAT process on its head — instead of the supplier charging VAT, the customer accounts for it themselves on their own return. It trips people up a lot, simply because it works so differently to normal VAT.

Subcontractor verification. Before paying a new subcontractor, contractors are generally required to verify them with HMRC to confirm their CIS status and deduction rate. Small step, easy to skip, and one HMRC does pay attention to.

Other considerations. Retentions (money a client holds back until work’s signed off), staged or milestone payments on longer contracts, and managing cash flow around CIS deductions all tend to loom larger in construction than in most other sectors. Even ordinary bookkeeping can be more involved, since job costs, materials and subcontractor payments often need tracking against individual contracts rather than just the business as a whole.

What are the Benefits of Using a Construction Accountant?

When an accountant deals with all this regularly, a few practical benefits tend to follow:

  • A better working understanding of how CIS, reverse charge VAT and subcontractor checks actually apply to your business
  • Fewer basic errors — wrong deduction rates, missed verification, VAT treated incorrectly
  • Support in staying compliant, since these are areas HMRC genuinely does pay attention to
  • A clearer picture of where your business actually stands financially, given how much CIS deductions and retentions can affect cash flow

None of this guarantees plain sailing, but it does mean less time spent second-guessing whether something’s been done right, and problems tend to get caught early rather than after HMRC has already asked a question.

Do I Need a Specialist Accountant?

It depends on your business. A small operation with straightforward subcontractor arrangements might do perfectly well with a competent general accountant, especially if you’re comfortable handling CIS and VAT admin yourself.

But if you’re regularly dealing with CIS, reverse charge VAT, several subcontractors, or you’ve ever found yourself unsure whether something was handled correctly, that’s usually a sign construction-specific knowledge would genuinely help. Not because a general accountant is doing a bad job — just because this is an area where sector experience really does make a difference.

This is exactly the kind of support the team at Magnum Accountancy provides for construction businesses, helping with CIS, reverse charge VAT and the everyday accounting that comes with running a business in this industry.

If you’re not sure whether your current setup covers what your business actually needs, it’s worth having that conversation rather than assuming everything’s fine.

Book a free 30-minute call with Daxa at Magnum Accountancy. /book-a-free-call/
Manufacturing Accounting Records: What to Keep

manufacturing accounting records

Manufacturing accounting records need to cover more than just sales and expenses. Manufacturers also need clear records for raw materials, stock, work in progress and production costs. Getting this right isn’t just about ticking a compliance box; it helps you see how the business is actually performing.

What Manufacturing Accounting Records Should a Business Keep?

At a high level, most manufacturers need records covering a few different things: money coming in and going out, the stock and work in progress sitting on the shop floor, how the business is performing month to month, and whatever HMRC expects you to hold onto for tax purposes.

What that looks like in practice varies with the size and complexity of the business — a small workshop and a larger production operation won’t run the same systems. But the categories below tend to come up for most manufacturers in some form.

Stock and Inventory Records

Stock is often one of the biggest assets — and one of the biggest costs — a manufacturing business carries, so getting the records right here matters more than in most industries.

That usually means keeping track of things like:

  • Raw materials and components you’re holding
  • Finished goods ready to sell
  • Stock movements, in and out
  • Stock valuation, since this feeds straight into your profit figures

Without decent stock records, it’s genuinely hard to know what you’ve actually got, what it’s worth, or whether stock is quietly going missing or sitting unused. Get the stock figures wrong and your reported profit can end up wrong too, since stock values directly affect the cost of sales in your accounts.

Work InProgress (WIP)

WIP just means goods that are partway through production — no longer raw materials, but not yet finished products ready to go out the door. For manufacturers, this can represent a genuinely large chunk of value sitting there at any given moment.

Tracking it matters because it affects how accurately your accounts reflect the real position of the business. Get WIP recording wrong and your accounts can end up understating or overstating both stock value and profit, depending on how the costs are being captured. Depending on the business, this might mean tracking materials used, labour applied, and overheads allocated to jobs still in progress.

Management Accounts and Reporting

Beyond what’s needed for compliance, most manufacturing businesses get real value from regular management accounts — essentially a more frequent, business-focused look at the numbers than annual accounts alone can give you.

Done well, management accounts help you keep an eye on:

  • Revenue, and how it’s tracking against what you expected
  • Costs — materials, labour, overheads
  • Profitability, overall and by product line or job where that’s relevant
  • Cash flow, which can get tight in manufacturing given how much money often sits tied up in stock and WIP
  • General business performance, so problems get spotted before they turn into serious ones

This is really where the difference between “records for HMRC” and “records for running the business” shows up. Both matter, but management accounts exist to help you make better decisions day to day, not just to satisfy a filing requirement.

HMRC Requirements and a Practical Checklist

Separately from running the business day to day, HMRC generally expects records that support your tax returns and VAT position (where applicable), kept for a certain period of time. Exactly what’s required, and for how long, can depend on your business structure and circumstances, so it’s worth checking what applies to you rather than assuming it’s the same for everyone.

As a general starting point, most manufacturing businesses will want to hold onto:

  • Sales and purchase records
  • Stock and inventory records
  • WIP records
  • Payroll records, where you employ staff
  • Expense records
  • Bank record
  • Invoices and receipts
  • VAT records, where applicable
  • Management accounts and other internal reporting

Think of this as a general guide rather than a fixed requirement for every business — what you actually need depends on how your business operates.

Keeping all of this organised isn’t always easy alongside running day-to-day production, which is exactly where working with an accountant who understands manufacturing, like the team at Magnum Accountancy, tends to help — both with staying compliant and with actually making sense of what the numbers are telling you.

If you’re not sure whether your current record-keeping covers what your business needs, it’s worth getting that properly checked.

Book a free 30-minute call with Daxa at Magnum Accountancy. BOOK A FREE CALL
Rental Property Limited Company: Is It Worth It?

rental property limited company

For landlords considering a rental property limited company, the right choice depends on how many properties they own, what they plan to do with the rental income, and how those properties are financed. For some landlords, a company can genuinely work in their favour. For others, it can add cost and admin without much to show for it. There’s no one-size-fits-all answer here.

Why Might a Landlord Use a Limited Company?

The reason this question comes up so often is tax efficiency, particularly for higher-rate taxpayers or landlords with a growing portfolio. Holding property through a limited company can, in some circumstances, work out more tax-efficient than owning it personally — though whether that’s true for you depends a lot on your income, your plans, and the properties themselves.

Long-term planning is the other big driver. If you’re the kind of landlord who wants to keep reinvesting rental profits into buying more property, rather than taking the income out to live on, a company structure sometimes suits that better. There’s also succession planning to think about — shares in a company can, in some cases, be easier to pass on or restructure than a handful of individually-owned properties.

None of this makes a limited company the automatic right answer. It just explains why so many landlords end up asking the question.

What Are The Potential Advantages?

A few benefits tend to come up in these conversations:

  • Profit extraction can potentially be more tax-efficient, depending on how you draw money out and your own personal tax position
  • Landlords can reinvest profits within the company, which suits those who don’t need the rental income personally.
  • It’s a separate legal structure, which can be handy for succession and estate planning
  • There’s more flexibility for growing a portfolio, since a company can hold several properties under one roof, so to speak

Whether any of this actually benefits you depends entirely on your own circumstances — worth properly exploring rather than assuming.

What Are The Potential Disadvantages?

There’s a flip side too, and it’s worth being just as clear-eyed about the costs.

SDLT implications.When you move properties you already own personally into a limited company, HMRC generally treats the transfer as a sale to the company. This can trigger Stamp Duty Land Tax on the transfer. That’s a real cost, and the amount depends on the property and your circumstances, so you should check the position carefully before making any transfer.

Mortgage considerations. Limited company mortgages don’t work the same way as personal buy-to-let ones. Rates, availability and lender criteria all vary, and if your properties currently sit on personal mortgages, moving them into a company can mean redeeming those and arranging fresh company-level finance — not always a quick or cheap process.

Additional administration. A company has its own filing obligations sitting alongside your personal tax return. In practice, that usually means:

  • Annual accounts and a confirmation statement filed with Companies House
  • A separate company tax return
  • Keeping proper company records, and in most cases running a separate business bank account

Accounting and filing responsibilities. All of this generally costs more than running properties personally, accountancy-wise — so it’s worth weighing that ongoing cost against whatever tax benefit you might be getting.

Is a Rental Property Limited Company Right for Me?

Rather than jumping straight to “should I”, it helps to sit down with a few honest questions first:

  • How many properties do I own now, or plan to buy down the line?
  • Do I actually need the rental income to live on, or would I rather reinvest the profits?
  • What’s the long game — growing the portfolio, passing it to family, or eventually cashing out?
  • What financing do I already have, and how would a company structure affect it?
  • Am I genuinely up for the extra admin and accountancy costs a company brings?

There isn’t a universal answer. What works brilliantly for a landlord with a large, growing portfolio might be overkill for someone with one or two properties they’re happy to hold for years. It really is a decision you should assess individually, and the team at Magnum Accountancy regularly helps landlords think it through — looking at the whole picture, not just the tax angle.

If you’re considering a rental property limited company, it’s worth getting advice tailored to your situation before making any changes.

Book a free 30-minute call with Daxa at Magnum Accountancy. /book-a-free-call/
IR35 Status for IT Contractors: Inside or Outside?

IR35 status for IT contractors

Understanding your IR35 status is important for IT contractors working through a limited company or personal service company. Whether an engagement falls inside or outside IR35 depends on the actual working relationship, not one factor alone. No single factor settles it on its own. It’s the overall picture that counts.

What Is IR35 Status for IT Contractors?

IR35 is tax legislation that targets contractors HMRC considers similar to employees. It applies even when they operate through their own limited company or personal service company (PSC).

If HMRC classifies an engagement as “inside IR35”, the income is broadly taxed in a similar way to employment income, rather than in the more tax-efficient way most contractors are set up for. “Outside IR35” means the contractor’s company can generally receive payment and pay tax as an independent business, as intended.

For IT contractors, this question comes up often because contracts can run for months. Contractors may also work within a client’s systems or premises, making their IR35 status harder to determine. That’s exactly why it helps to understand what HMRC and tribunals actually look at.

What Factors Affect IR35 Status for IT Contractors?

There’s no neat checklist that spits out a definitive answer, but a few areas keep coming up as relevant.

Substitution. Could the contractor genuinely send someone else to do the work instead of them? A substitution clause can be a relevant factor, but only if it’s a real, unrestricted right — one the client would actually go along with in practice. A clause in the contract that neither party would realistically use carries much less weight than one that either party can genuinely exercise.

Control. This is about who decides how, when and where the work happens. If the client’s dictating hours, methods and day-to-day direction in a way that looks a lot like managing an employee, that may indicate an inside-IR35 relationship. More freedom over how the work actually gets delivered tends to point the other way.

Mutuality of obligation (MOO). In plain terms: is there an ongoing expectation that the client will keep offering work and the contractor will keep accepting it, beyond what’s already agreed for the current project? MOO on its own doesn’t decide status — but whether that ongoing obligation exists is still one piece of the wider puzzle.

Other factors. HMRC and tribunals have also weighed things like financial risk, whether the contractor supplies their own equipment, whether they work for more than one client, and how embedded they are in the client’s organisation. None of these tips the balance alone — they all feed into the bigger assessment.

Why the Contract Isn’t the Whole Story

A well-written contract helps, but it’s not the final word. What HMRC really cares about is how the engagement works in reality — the actual working practices — not just what’s written on paper.

Say a contract includes a substitution clause and claims the contractor has full control over their methods, but in reality, the client closely directs the contractor, sets their working hours, and has never allowed them to send a substitute. In that situation, it’s the real working relationship that tends to count, not the wording.

That’s why it’s worth looking at the contract and the day-to-day reality of the engagement side by side, rather than assuming a well-drafted contract settles things by itself.

How Can IT Contractors Protect their IR35 Position?

A handful of practical steps can put you in a stronger, better-evidenced position:

  • Actually read contracts before signing them, rather than assuming a standard template has you covered
  • Check the contract reflects how the engagement will genuinely operate, not how you’d like it to look on paper
  • Keep hold of evidence of working practices — emails, correspondence, examples of autonomy or substitution — in case your position is ever questioned
  • Revisit your IR35 assessment if the engagement changes, since a shift in working practices can shift the picture too
  • Get professional advice when things aren’t clear-cut, particularly on longer contracts or ones where you’re closely embedded with the client

This isn’t something worth guessing at — getting it wrong can have real financial consequences. It’s an area the team at Magnum Accountancy regularly helps IT contractors work through, looking at both the contract and the working practices together so you end up with a clearer, better-evidenced position either way.

If you’re not sure where a particular engagement stands, it’s worth talking it through with someone who understands the detail rather than relying on assumptions.

Book a free 30-minute call with Daxa at Magnum Accountancy. /book-a-free-call/
Which Healthcare Business Expenses Can You Claim?

Healthcare business expenses

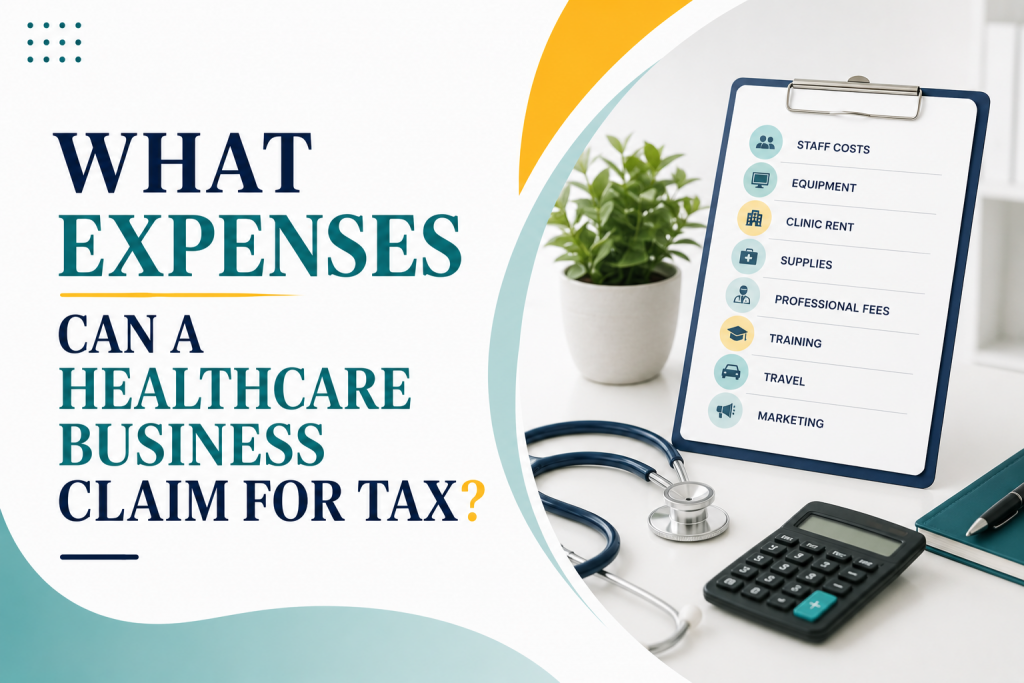
Yes — a healthcare business can generally claim tax relief on costs that genuinely relate to running the practice, from staff wages to clinical equipment and premises costs. But “generally” is doing a lot of work in that sentence, because the exact treatment really does come down to the nature and purpose of each expense.

So What Actually Makes Something “Allowable”?

HMRC’s test is whether a cost is incurred “wholly and exclusively” for the business. Translated out of tax-speak: the expense has to be genuinely for running your practice or clinic, not for your own benefit on the side.

A couple of things fall out of that:

  • If something’s used for both business and personal reasons, only the business slice of it is usually allowable
  • It doesn’t have to be essential — just reasonable, and clearly connected to the business
  • Bigger purchases that last (equipment, for instance) tend to get treated differently to everyday running costs

And this applies whatever structure you’re operating under — sole trader, partnership, or limited company — though how the relief actually gets given can vary between them.

Staff Costs and Professional Fees

For most healthcare businesses, staff costs are one of the biggest lines in the accounts, and they’re generally allowable. That covers things like:

  • Salaries, wages and employer’s National Insurance
  • Locum or agency staff
  • Employee pension contributions
  • Fees for accountants, solicitors and other professional advisers

One area worth flagging: if you’re a director paying yourself a salary through a limited company, that’s treated quite differently to a sole trader taking drawings from the business. It’s genuinely worth getting advice on this one, because it affects your personal tax as much as the business’s.

Equipment, Premises and The Everyday Running Costs

Clinical equipment — examination tables, diagnostic tools, sterilisation kit, that sort of thing — will usually attract some form of tax relief. Bigger items, though, often get treated as capital expenditure rather than a straightforward deduction, so don’t assume every purchase works the same way.

Premises and office costs tend to be allowable too:

  • Rent, business rates and utilities for your clinic or practice
  • Repairs and maintenance
  • A home office, where part of the home is genuinely used for the business
  • Office supplies, software and IT costs

Wherever premises or equipment get used for both business and personal purposes, only the business share is normally allowable — so it’s worth keeping a note of how something’s actually used, not just what it cost.

Insurance, Training, Marketing and Travel

Professional indemnity insurance, public liability cover, and subscriptions to relevant professional bodies are generally allowable — they’re pretty much a condition of practising in healthcare. Training and CPD that keeps your existing skills up to date usually falls into the same category.

Where it gets trickier is training that gives you a brand-new qualification rather than updating one you already have — that can be treated differently, so it’s worth checking before you assume a course qualifies.

Marketing costs — your website, local advertising, printed materials — are generally fine, since they’re clearly there to bring in business.

Travel tends to catch people out. Journeys between different work sites, or to see patients, are usually allowable. The commute from home to your regular workplace generally isn’t, and if a vehicle does double duty for business and personal use, the personal portion needs to come out of any claim.

Keep The Paperwork — and Know What Doesn’t Count

Whatever you claim, HMRC will expect receipts and invoices. These should show what you bought, when you bought it, and why you needed it for the business.Good records aren’t just box-ticking — they make life much easier if HMRC ever asks questions, and they make your annual accounts more accurate in the process.

A few things people often assume are allowable but aren’t, or only partly are:

  • Everyday clothing, even if you happen to wear it at work (specific clinical or branded workwear is a different story)
  • Client entertaining — generally not allowable for tax purposes
  • Personal costs run through the business, even now and then
  • Fines or penalties, which are never allowable

Healthcare businesses tend to have a real mix of clinical, staffing and premises costs, and it’s easy for the lines to blur — especially around equipment, home working and vehicles. This is where a healthcare-focused accountant can make a real difference. The team at Magnum Accountancy can help you claim legitimate expenses while staying within HMRC rules.

If you’re unsure whether an expense qualifies, check before claiming it. The answer often depends on your circumstances and how your business operates.

Book a free 30-minute call with Daxa at Magnum Accountancy. /book-a-free-call/
Engineering Business KPIs: 5 Financial Metrics to Track

Engineering Business KPIs

Engineering business KPIs help you understand whether your projects are making money before year end. Most engineering business owners know their turnover and annual profit, but the right KPIs reveal problems while there’s still time to fix them. Gross margin and net profit are fine as a scoreboard, but they tell you the result long after the game’s finished. For project-based work, that’s often too late to matter.

Who Should Track Engineering Business KPIs

This is aimed at engineering businesses running project or job-based work, whether that’s contract manufacturing, mechanical or electrical engineering, or specialist fabrication. If most of your revenue comes from quoted jobs rather than predictable repeat sales, these numbers matter more than the standard set most accountants default to.

Engineering Business KPI: Quote-to-Win Ratio

This measures how many quotes actually turn into won jobs. It has a direct bearing on pricing. A very high win rate can mean you’re underpricing and leaving margin on the table. A very low one means you’re spending time quoting work you were never likely to land. Tracking this by client type or job size often shows where your pricing is genuinely competitive.

Engineering Business KPI: Job Costing Accuracy

This compares what a job actually cost against what you quoted. Most firms quote materials reasonably well, since those costs are visible. Labour and overhead are where estimates tend to drift, particularly on jobs that hit complications. Tracking the gap between quoted and actual cost, job by job, shows where estimating needs tightening, rather than just accepting overruns and hoping the average works out.

Engineering Business KPI: Work-in-Progress Value

This is the value of work completed but not yet invoiced, real value sitting outside your bank account, and easy to lose track of on longer projects. A business can look healthy on paper while genuinely struggling for cash, simply because a large chunk of completed work hasn’t been billed. A current WIP figure gives an honest picture of where you actually stand.

Engineering Business KPI: Overhead Recovery Rate

This checks whether job pricing is actually covering fixed costs, workshop rent, equipment, insurance, admin, not just materials and labour. It’s easy to overlook, because jobs can look profitable individually while the business as a whole isn’t covering its overheads. A recovery rate consistently below target usually means the pricing model needs revisiting, not that you simply need more work.

Engineering Business KPI: Debtor Days

This measures how long it takes to get paid once a job’s invoiced. Engineering businesses often extend generous payment terms to keep clients happy, but slow payers can quietly starve a business of cash even while it looks profitable on paper. Tracking this by client makes it easier to spot which relationships cost more in cashflow than they’re worth.

Why Engineering Business KPIs Matter

Take a mechanical engineering firm that looked solidly profitable at year end, turnover up, margin steady. A closer look at job-level data told a different story. Two large clients were regularly paying over 60 days late, work-in-progress had crept up for months unnoticed, and one job type was consistently running 15% over its quoted labour cost. None of this showed up in the annual accounts. It only became visible once someone looked job by job, rather than at the business as a whole.

Track Engineering Business KPIs Before Year End

Waiting for annual accounts to reveal a problem means the problem’s already happened. Tracking these five numbers regularly gives you the chance to catch it while there’s still time to act.

If you’d like help setting up KPI tracking that fits how your engineering business runs, Magnum Accountancy offers a free call to talk through where to start. Book yours today.